Roof and access work
Falling objects, access equipment, penetrations and work at height can affect occupants, visitors and surrounding property.
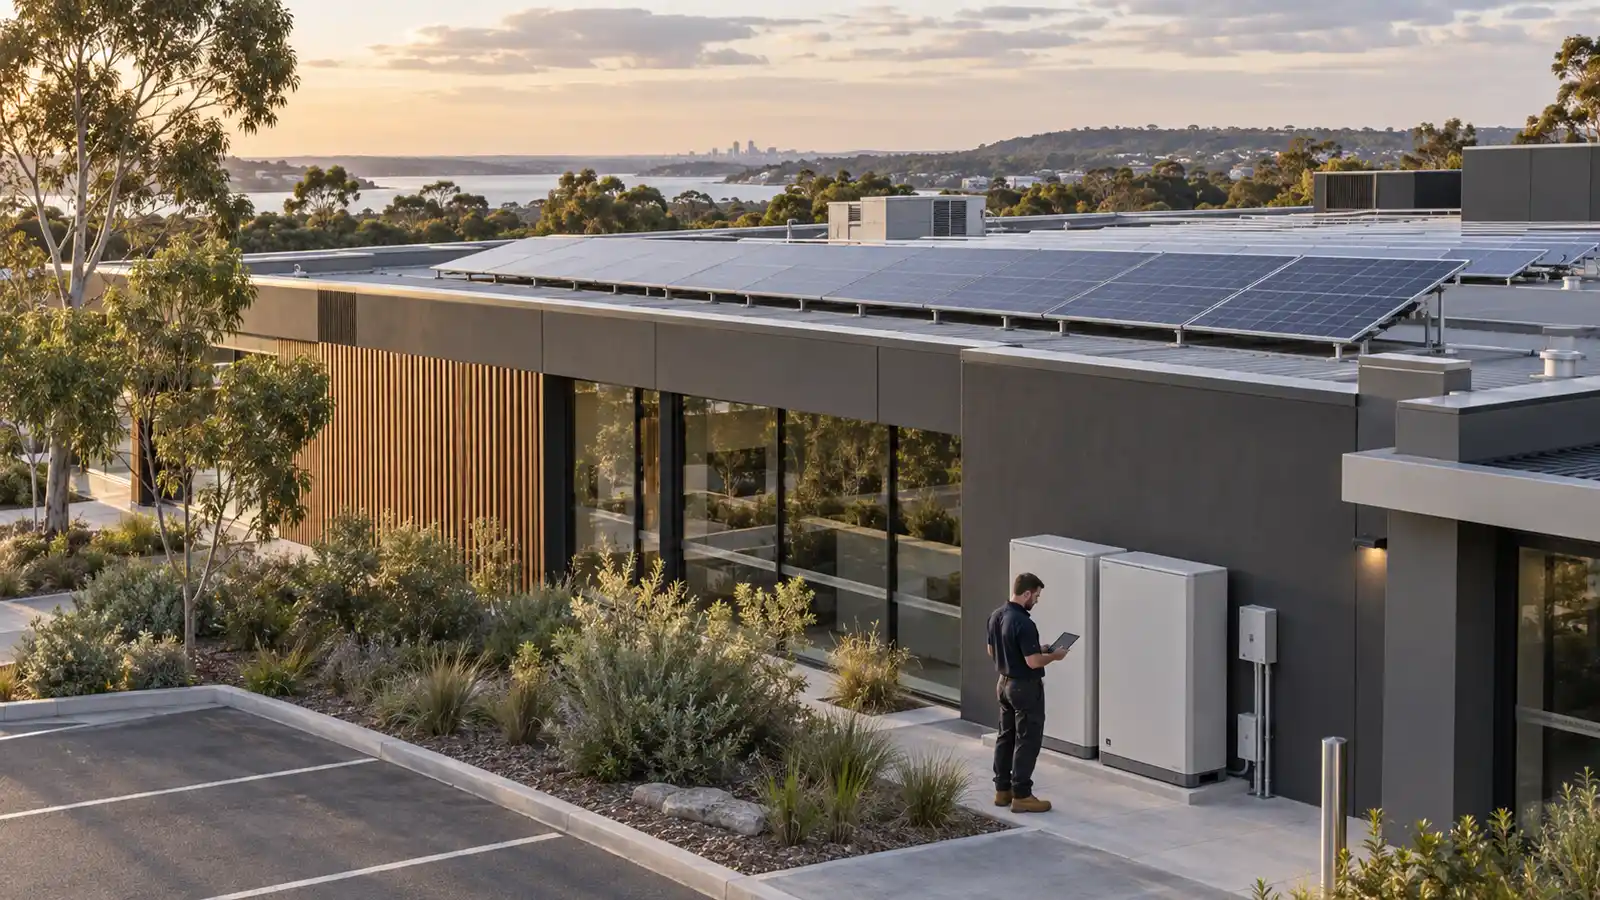
Build the liability submission around the roof work, electrical work, supplied products, subcontractors and contract limits.
PI
Professional advice
PL
Work on site
D&C
Design responsibility
Recognition
THE SHORT ANSWER
What does public liability insurance do for a solar installer?
Public and products liability may respond when a solar installer is legally liable for covered third-party injury or property damage arising from its declared work or products. It does not automatically pay to correct defective work, meet every contractual promise or cover professional advice and design.
Tank's historical solar enquiries include one where a higher public liability limit was requested and several where insurers declined citing occupation, and subcontractor use was part of the submission. We verify those details rather than treating one limit or policy structure as standard.
Public and products liability is generally concerned with covered third-party injury and property damage. The claim still has to fall within the insuring clause and avoid applicable exclusions.
Falling objects, access equipment, penetrations and work at height can affect occupants, visitors and surrounding property.
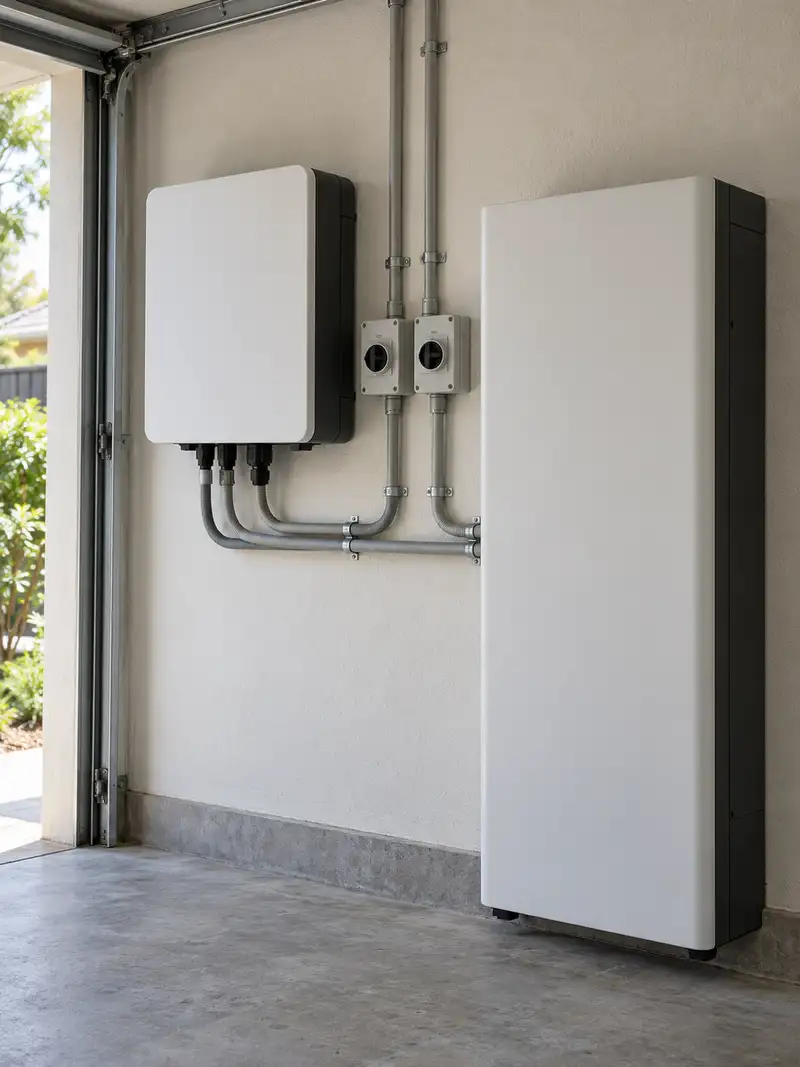
Switchboard, cabling and connection work can interact with property already in place. Confirm how damage to the part being worked on is treated.
Roof penetrations and incomplete work can lead to allegations of water damage. A liability policy should not be treated as a guarantee of the contractor's own work.
Allegations may arise after handover from supplied products or completed installation. Products and completed-operations wording needs to match the declared work.
Identify the entity promising the finished installation, invoicing the customer and carrying the project obligations.
State whether subcontractors perform electrical installation, roof work, design, commissioning or the entire job.
Insurers may ask about written agreements, licence and accreditation checks, certificates of currency, induction and supervision.
A policy may address the named insured's liability arising from subcontracted work without making each subcontractor an insured. Read the definition and endorsements.
HOW WE ASSESS THE RISK
Tank's historical solar enquiries include one where a higher public liability limit was requested and several where insurers declined citing occupation, and subcontractor use was part of the submission. We check the contract requirement and the work performed instead of presenting one limit as standard.
This is a fact-find method, not a promise of insurer acceptance.
Retail, design, installation, commissioning, maintenance and monitoring software are listed separately.
Employees, subcontract installers or both, and how subcontractors are engaged.
The limit a contract or accreditation body asks for, checked against the work you perform.
Supply the insurance clause from tenders, head contracts, leases or site-access agreements rather than selecting a limit by assumption.
Broad indemnities, waiver of subrogation, principal indemnity and liability accepted beyond common law need insurer review.
Turnover, payroll, staff, highest contract value, residential/commercial mix, building height and territories help insurers assess the exposure.
List solar, battery, general electrical, retail, design, project management, maintenance and monitoring activities so the schedule is not narrower than the work.
CASE STUDIES
Anonymised past placements from Tank's records. They are not quotes: your premium and terms depend on your work, claims history and the insurer's assessment.
Premiums and outcomes described are specific to each client and indicative only. Your own terms will depend on your circumstances and the insurer.
Technical and accreditation context checked 9 September 2026; SAA insurance evidence requirements checked 10 October 2026: Clean Energy Regulator, Solar Accreditation Australia and business.gov.au insurance guidance.
PRACTICAL QUESTIONS
SOLAR AND BATTERY INSURANCE LIBRARY
Tell us what you design, supply, install, commission and maintain. We can then identify which liability sections may be relevant and approach insurers with an accurate description of the work.