What Underwriters Need to Quote a Large Block of Units
A large block is priced by a person reading your submission, not an online rating engine. The more of this list you can send with the enquiry, the fewer questions come back and the sooner terms arrive.
6
Groups an underwriter asks about
6-8 wks
Best start before renewal
48-72h
Usual turnaround, all info in
Recognition
THE SHORT ANSWER
To quote a block of 10 or more units, or a building worth $3 million or more, an underwriter needs six groups of information: the building, its value, the rent roll, its fire protection and security, its claims and insurance history, and the exact owner on the title. A complete submission is the part of the timeline you control, and it can let an underwriter price the building on the first pass.
You don't need every item to start. Send what you have, including your current schedule, and we'll work through the gaps with you. For what changes at this size, see insurance for large blocks.
01THE CHECKLIST
Six Groups of Information an Underwriter Asks For
This is the same list we work through on a fact find. If you have your current schedule and a rent roll, you already have half of it.
The Building
- Full address
- Number of units, and the mix of bedrooms and bathrooms
- Storeys, basement and any lift
- Year built, and any major additions
- Walls, floors and roof construction
- External cladding type, or 'unconfirmed'
- Rewiring and replumbing dates on older buildings
- Heritage listing, pool, solar or other features
The Value
- Building sum insured, and how it was set
- Date of the last replacement cost valuation, if any
- Contents in common areas (carpets, furnishings, equipment)
- Plant: lifts, pumps, fire panels, gates
The Income
- Weekly rent per unit, or the annual rent roll
- How many units are let, and any vacancy
- Whether a licensed property manager manages it
- Long-term leases, short-stay, or a mix
- Any commercial use in the building
The Protection
- Smoke alarms, sprinklers, hose reels, fire panel
- Annual fire safety statement, or your state's equivalent
- Monitored alarm, CCTV, deadlocks, secure entry
- Basement drainage and sump pumps
The History
- Claims in the last five years, and what was fixed
- Any insurance refused, cancelled or not renewed
- Current insurer, schedule and renewal date
- Known defects, works in progress or planned renovations
The Owner
- Insured name exactly as on the title
- For a trust: the trustee and the trust's name
- For an SMSF: the fund's trustee; under an LRBA, the bare trustee with the SMSF trustee noted
- Lender to be noted as an interested party
- Preferred excess and start date
READY TO SEND
Start with the form, then send the schedule
The form takes the unit count and building value first. Our team will follow up for the rest, or call 02 9000 1155 if your renewal is close.
02WHY IT MATTERS AT THIS SIZE
Missing Answers Become Assumptions
When an underwriter doesn't have an answer, they either ask and wait, or price on a cautious assumption. On a large block, both cost you: time in the first case, premium in the second.
A complete submission also shows the building at its best. Sprinklers, a recent rewire or a current valuation only help if the underwriter knows about them.
-
The sum insured basis
Say how the figure was set: a valuation, a builder's estimate, or last year's figure indexed. An underwriter treats each one differently.
-
The rent roll
The figure that sets the loss of rent limit. See loss of rent for a whole block for how to work it out.
-
The history, told in full
Claims and any refused or non-renewed insurance, with what's been fixed since. If your insurer won't renew, see what to do after a non-renewal.
CLIENT SUCCESS
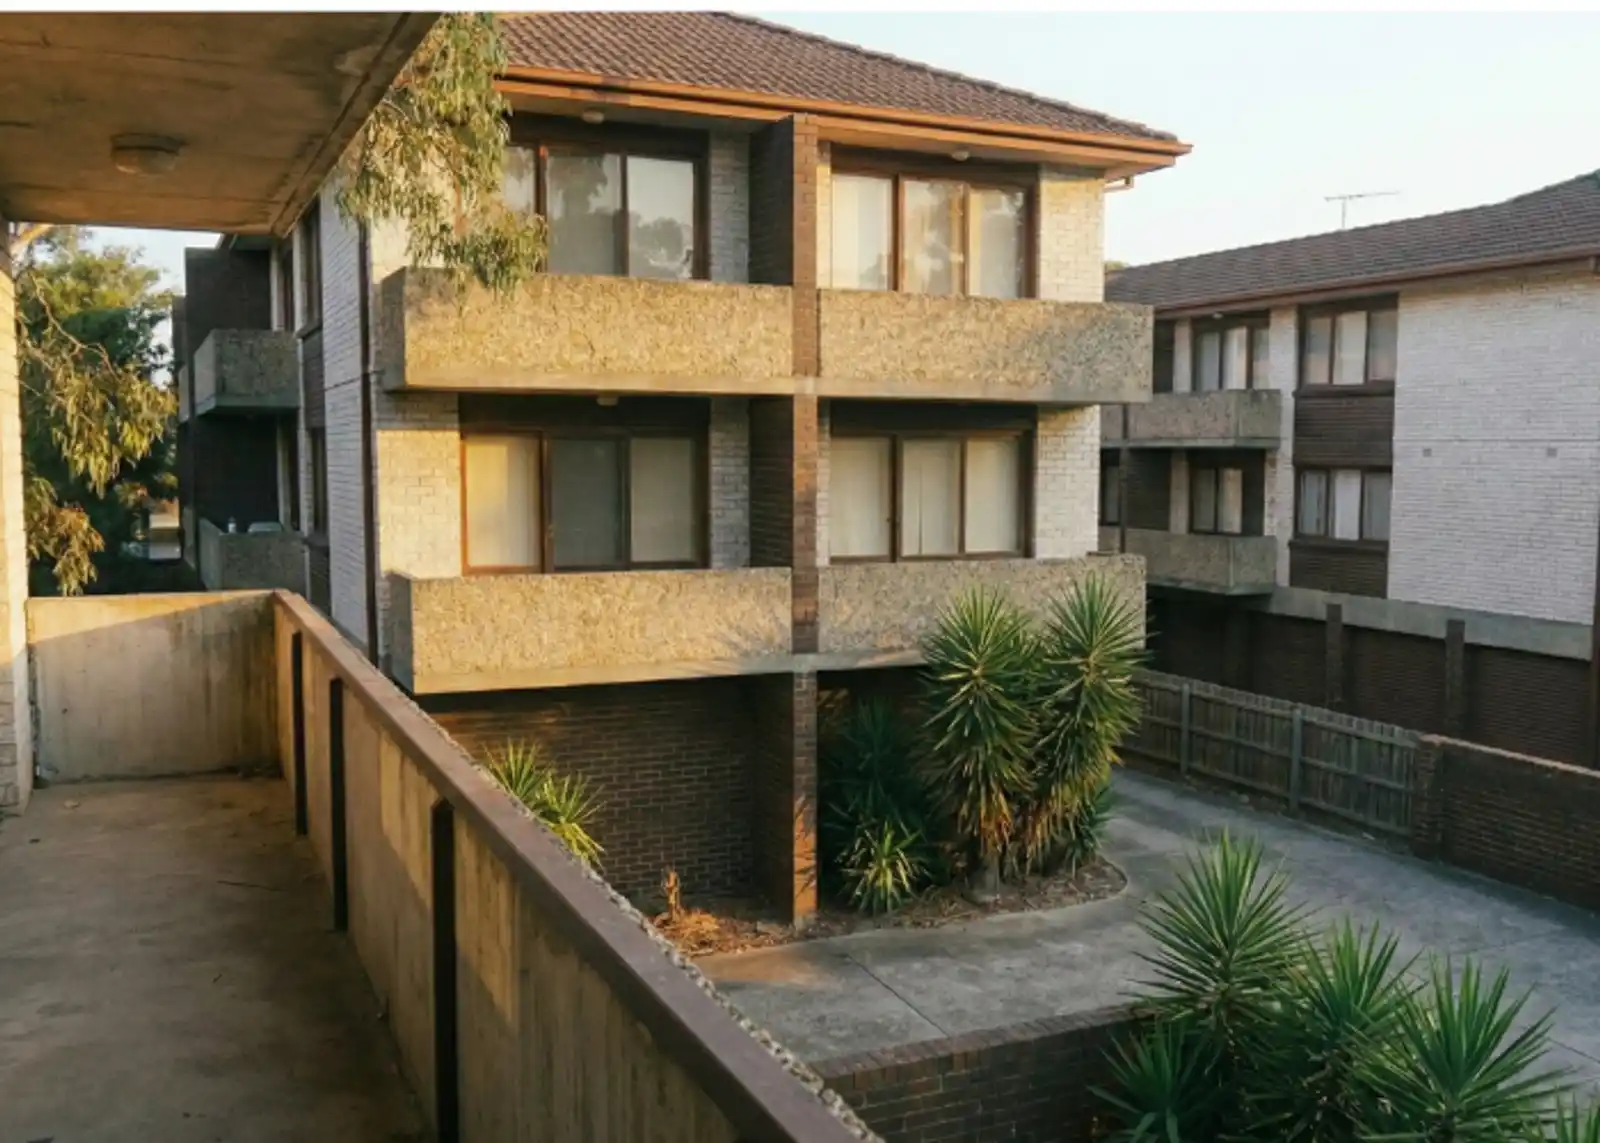
Complete Submissions: How These Blocks Were Placed
Recent Tank placements, anonymised. Premiums are approximate gross figures and reflect each risk at the time. They're not a guide to future pricing or turnaround.
Premiums and outcomes described are specific to each client and indicative only. Your own terms will depend on your circumstances and the insurer.
QUOTE CHECKLIST FAQS
Common Questions About Quoting a Block of Units
RELATED COVER & GUIDES
More on Insuring a Large Block
Have the schedule but not the rest? Send it anyway and we'll work through the gaps with you.
Talk to Our Team →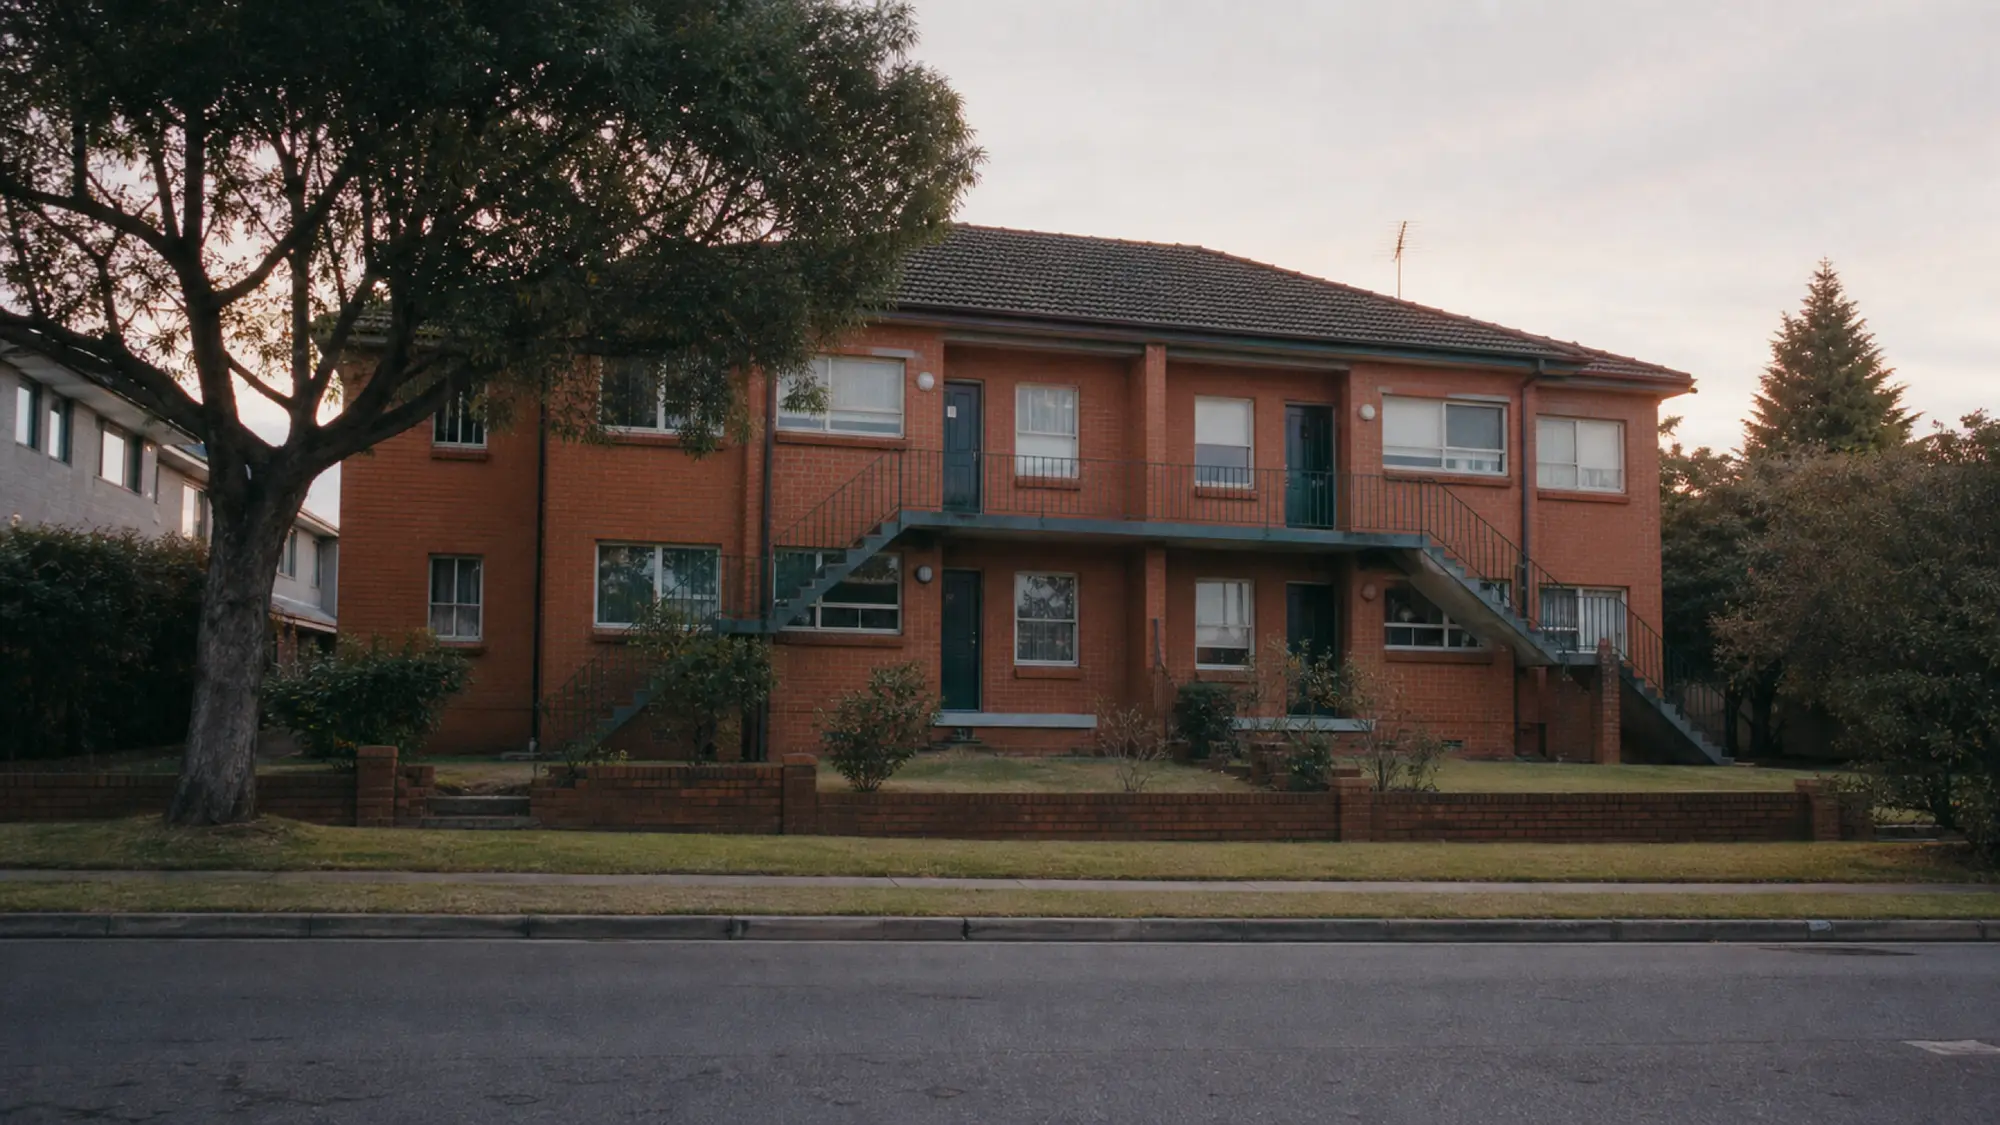
Start a Large Block Quote
Send the unit count, the building value and your current schedule. We'll build the submission with you and take it to the markets that write whole blocks.