Home Insurance While a Subdivision Is in Progress
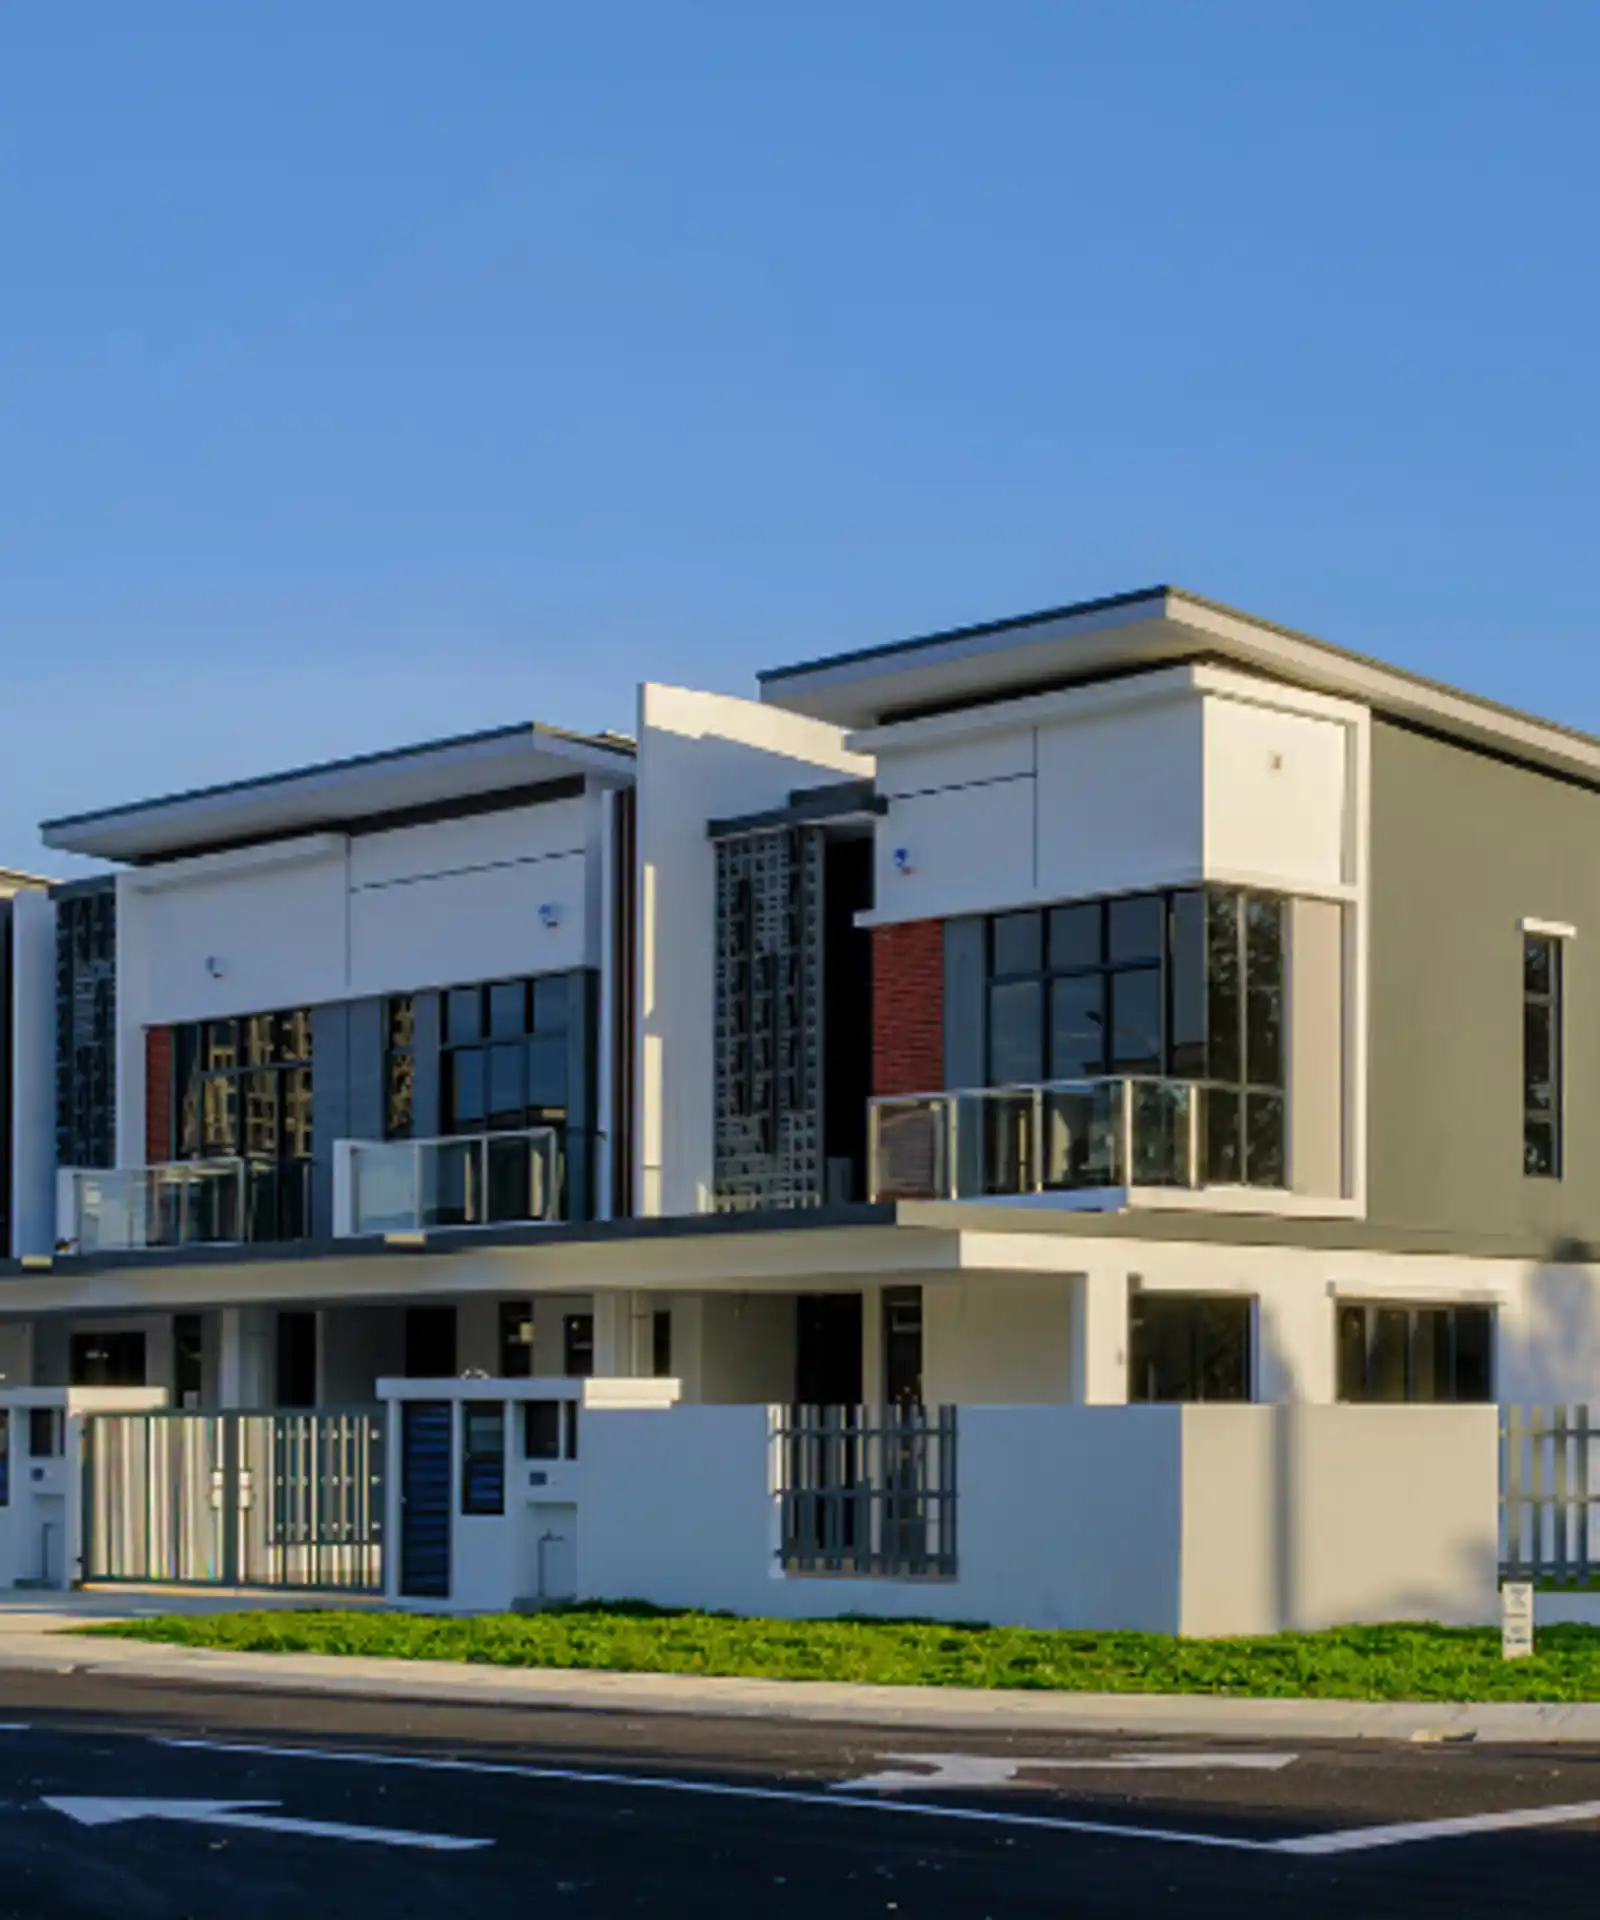
Two houses on one title today, two titles later. The property is insured as it legally stands, the lender is noted, and the policy is planned to split on registration day rather than scrambled when a certificate is asked for.
1 title
Insured as it legally stands today
$3.7-9K
Recent placed premiums
24-72h
With all information in hand
Recognition
THE SHORT ANSWER
Until a subdivision registers, two houses on one title are insured as one lot with two dwellings declared, in the owner's name, with the lender noted. Some markets write both on one policy, some only one policy per dwelling, and a few decline on the subdivision itself. On registration each new lot gets its own policy, sum insured and certificate. Appetite is case by case.
Tank arranges this across Australia, usually for an owner who has just built or bought and has a lender waiting on a certificate. The work is describing the lot as it legally stands, getting both dwellings and the lender onto the schedule, and booking the restructure for registration day.
01HOW IT RUNS
From One Title to Two: What Changes at Each Stage
A subdivision has a before, a during and an after, and the policy has to match each of them.
Before the plan registers: one title, two dwellings
Until the subdivision is registered, there is one lot with two houses on it, whatever the plans say. The policy names the owner of that lot, declares both dwellings with a rebuild figure for each, and notes the lender. Some markets will write both on one policy; some will only write one policy per dwelling; a few decline on the subdivision itself.
The lender's letter
A lender funding the build or the purchase usually wants cover from handover or settlement, with the lender named as interested party and a certificate of currency showing both dwellings. If the certificate shows one house on a two-house lot, it comes back. Give us the lender's exact name and what their letter asks for.
Handover with nobody living there yet
A builder's handover often lands weeks or months before anyone moves in. That is an unoccupied new build and it narrows the field further; on one recent placement four markets declined on unoccupancy alone. If that is your position, the unoccupied new build page covers it.
Registration day: one policy becomes two
When the plan registers, each new lot needs its own policy in the name of its owner, with its own sum insured and its own certificate. The interim policy is endorsed or cancelled pro rata and replaced. Tell us the expected registration date at the start so the restructure is planned rather than improvised.
Selling one lot, keeping the other
If one dwelling is being sold on registration, the buyer's settlement needs its own certificate and the seller's policy needs to stop covering the lot they no longer own. Two settlements on one week is common here and it is where a broker earns the call.
What the insurer will ask that the form does not
Where the subdivision is up to, who the surveyor and the council are, whether services are separated, whether each dwelling has its own street address yet, and whether either dwelling is or will be tenanted. Answer those up front and the referral moves; leave them out and it stalls.
SUBDIVISION QUOTE
Send the lot as it stands and the date it changes
Both dwellings, the rebuild cost of each, the lender's name and the expected registration date. We'll come back with terms and a plan for the split.
CLIENT SUCCESS
Two Subdivisions, Two Lenders, Two Placements
Recent Tank placements, anonymised. Premiums are approximate gross figures and reflect each risk at the time, not a guide to future pricing or turnaround.
Premiums and outcomes described are specific to each client and indicative only. Your own terms will depend on your circumstances and the insurer.
SUBDIVISION FAQS
Common Questions About Insuring a Property Mid-Subdivision
RELATED COVER & GUIDES
More on Two-Dwelling and Home Cover
Lender chasing a certificate that shows both dwellings? Send us the letter and the current schedule.
Talk to Our Team →
Get Cover for the Lot as It Stands
Both dwellings on the schedule, the lender noted, the split planned. Tell us where the subdivision is up to.