
High-Value Home Insurance
When the rebuild cost is above a million, the online form starts saying no. The house is fine; the product has a ceiling. We take it to the markets that write higher sums, with the sum insured set from a rebuild estimate rather than the price.
$1-3M
Sums insured on recent placements
$1M+
Where direct home products start to narrow
24-72h
With all information in hand
Recognition
THE SHORT ANSWER
A home with a rebuild cost above about $1 million is insured on a sum set from a rebuild estimate, not market value, with the markets that write higher sums. Direct products carry a ceiling and refer or refuse above it. Age, heritage construction, location, protection and the excess move the rate more than the sum itself, and a company-title building or a very large residence can be written as an Industrial Special Risks policy instead. Appetite is case by case.
Recent Tank placements ran from three $1 million new builds at approximately $2,400 each to a company-title building of owner-occupied units in Sydney's eastern suburbs placed as an ISR at approximately $19,300 after the previous insurer declined the renewal. The spread between quotes on the same house was roughly two to one.
01WHAT MOVES THE PLACEMENT
Six Things That Decide How a High-Value Home Gets Insured
The sum insured opens the conversation. These are the things that decide which markets stay in it.
Rebuild Cost Is Not Market Value
In Sydney and Melbourne the land is most of the price. A $4 million house on a $2.8 million block might carry a $1.2 million rebuild; a large house on a steep block with a pool, retaining walls and a slate roof can carry more than its price suggests. The sum insured comes from a rebuild estimate, not the contract or the valuation.
Where the Direct Products Stop
Direct home products carry a ceiling on the building sum insured, and above it the online form either refuses or refers. Above about $1 million the field starts to narrow; above $2 million it narrows quickly. That is not a judgement on the house, it is the product's limit, and it is why these placements go to markets that write higher sums every day.
Construction and Heritage Detail
Double brick, slate, sandstone, timber-framed verandahs and period joinery all push the rebuild cost and the time to rebuild. On one period building in Sydney's east, two markets declined on the sum insured alone before one specialist market approved it on referral.
Protection as a Condition
On higher sums insured, a monitored alarm, CCTV, deadlocks and key-operated window locks can be a condition of cover rather than a discount. The $3 million trust-owned build below carried monitored alarms and CCTV, and was rated on them.
The Excess You Choose
A higher excess does real work at this level. The same trust chose a $10,000 excess and the premium reflected it. If you can carry the first $5,000 or $10,000 of a claim, say so at the start; it changes which markets quote and what they quote.
When It Is Not a Home Policy at All
A company-title building of owner-occupied units, or a residence with a sum insured the home markets will not reach, can be written as an Industrial Special Risks policy instead. The eastern suburbs building below was. The cover is broader in some places and different in others, and it is a decision to make with the schedule in front of you.
HIGH-VALUE HOME QUOTE
Send the rebuild estimate, not the valuation
Address, construction, year built, the rebuild figure, the protections in place and the excess you'd carry. We'll tell you which markets are realistic before anything is submitted.
CLIENT SUCCESS
From $1 Million to an Eastern Suburbs ISR: How These Get Placed
Recent Tank placements, anonymised. Premiums are approximate gross figures and reflect each risk at the time, not a guide to future pricing or turnaround.
Premiums and outcomes described are specific to each client and indicative only. Your own terms will depend on your circumstances and the insurer.
HIGH-VALUE HOME FAQS
Common Questions About Insuring a Home Above $1 Million
RELATED COVER & GUIDES
More on Home and Property Cover
Renewal declined or the online form refused the sum insured? Send us the schedule and the rebuild estimate.
Talk to Our Team →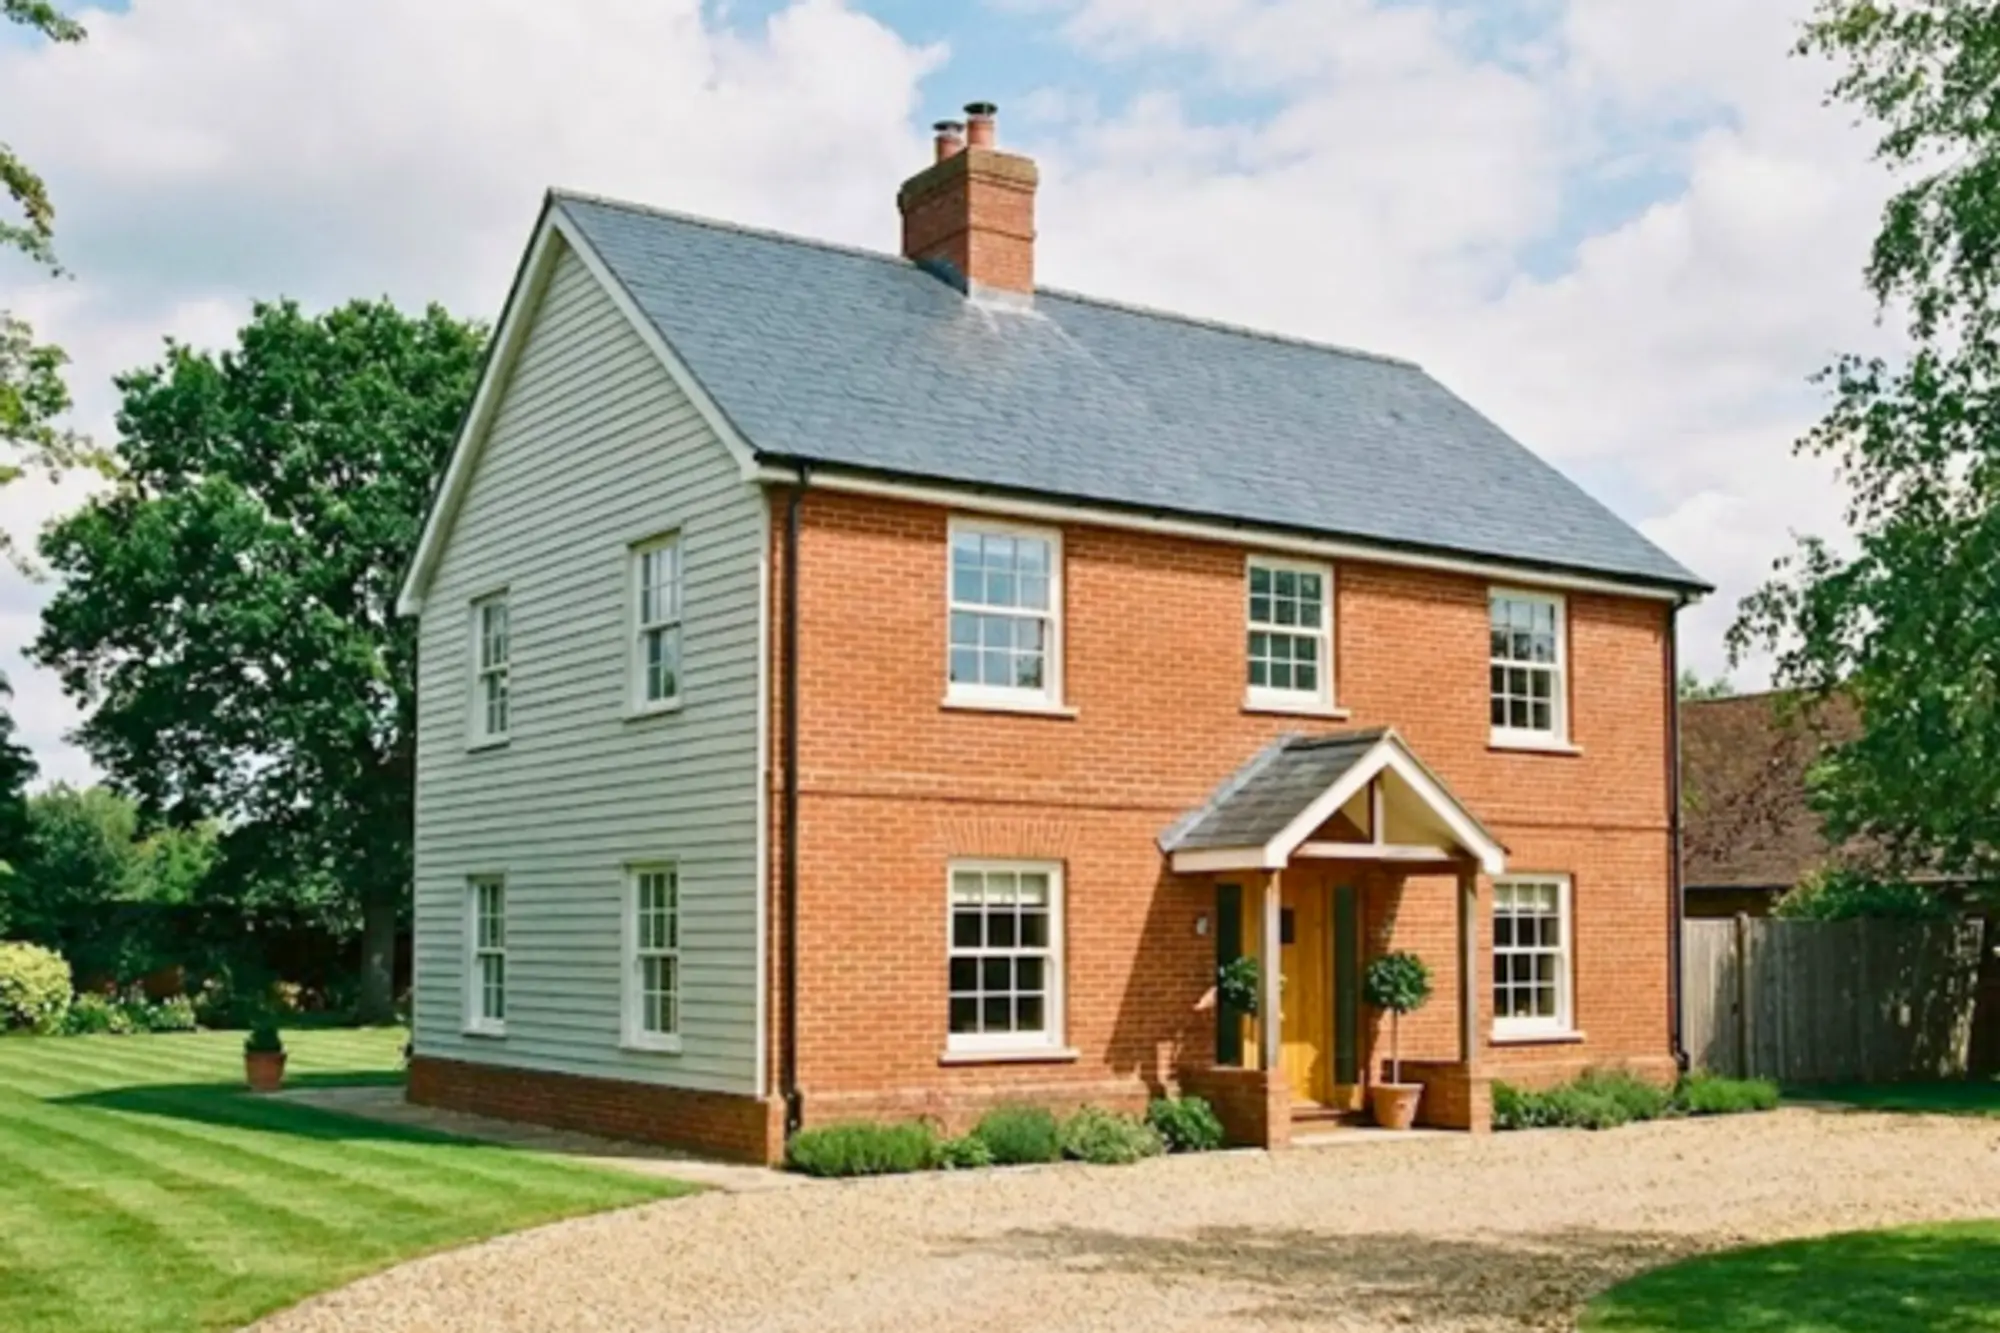
Get a High-Value Home Insurance Quote
The right sum insured, the markets that write it, and a straight answer on whether it is a home policy or an ISR.