
Heritage-Listed Rental Property Insurance
A listing changes two things: what the building costs to put back, and which insurers will write it. We set the sum insured to a heritage rebuild and place the risk with markets that write listed residential property.
Nearly 2x
Rebuild vs purchase price, one SA case
$3-4.2K
Recent annual premiums
48h
Possible with everything ready
Recognition
THE SHORT ANSWER
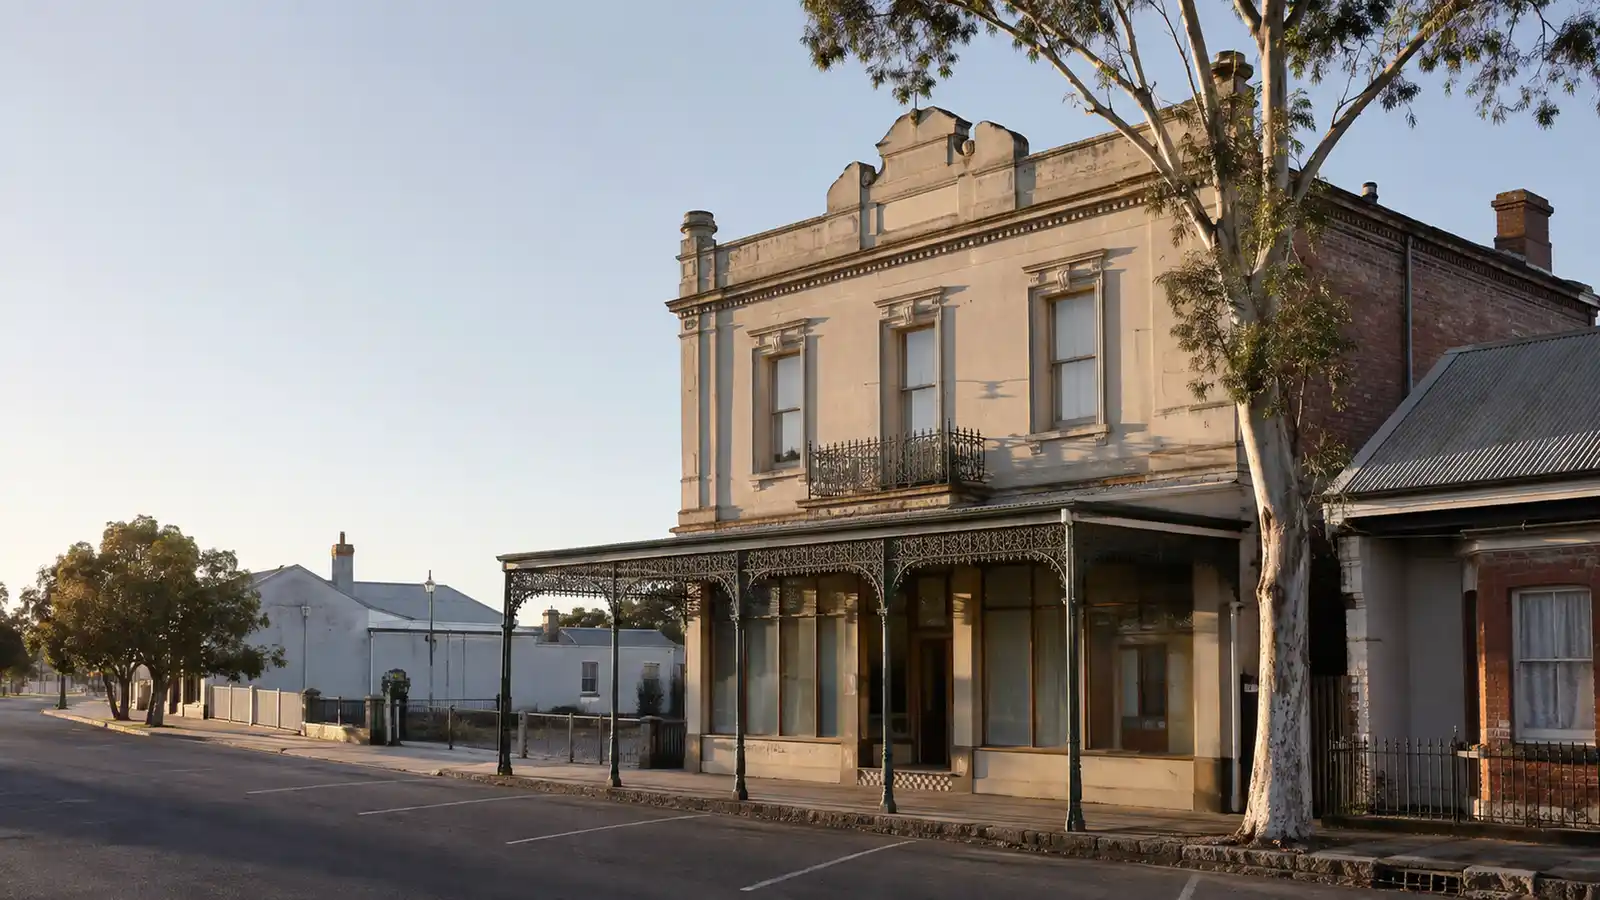
A heritage-listed rental property can usually be insured. The listing changes two things: the rebuild cost, because the building is reinstated like for like with conservation approvals, and the market, because some standard landlord products don't write listed buildings while specialist and some mainstream markets do, with the right sum insured. Getting the sum insured right is what decides whether a heritage rebuild is funded.
Tank arranges landlord cover for heritage-listed houses, terraces, converted buildings and residential blocks across Australia. We set the sum insured against a heritage rebuild rather than the purchase price, document the rewiring and replumbing history, and refer the file to the underwriters that assess listed buildings on their merits. For a heritage building with a shop or office in it, see our heritage mixed-use property page instead.
01WHAT THE LISTING CHANGES
What Landlord Cover Looks Like on a Listed Building
The cover is ordinary landlord cover. What the listing changes is how each part of it has to be set up, subject to policy terms, limits and exclusions.
| What's covered | What the heritage listing changes |
|---|---|
| Building - fire, storm, escape of water, impact and other insured events | Reinstatement is like for like: heritage materials, matching methods and conservation approvals, all of which sit inside the sum insured |
| Total loss and cash settlement | A cash settlement may be offered, but the heritage body can still require the listed element, often the facade, to be reinstated as it stood |
| Loss of rent after insured damage | The rebuild period runs longer on a listed building, so the limit and indemnity period should reflect a heritage timeline |
| Legal liability as property owner | Unchanged by the listing; rated on occupancy and condition like any rental |
| Tenant damage and rent default (where selected) | Availability depends on the market that writes the building, so it's confirmed once the placement route is clear |
| Fences, walls, outbuildings and other improvements | Listed fences, gates and outbuildings carry the same reinstatement conditions as the house and are often sub-limited |
HERITAGE RENTAL QUOTE
Get a listed rental property properly insured
Tell us what's listed, when it was rewired and replumbed, and what it would cost to rebuild. We'll take it to the markets that write heritage residential property.
02SETTING THE SUM INSURED
Six Things That Decide Whether a Heritage Rebuild Is Actually Funded
Finding an insurer is half the job. The other half is making sure the policy would pay enough to put a listed building back.
Like-for-Like Materials and Methods
A listed building is usually reinstated with the materials and construction methods it was built with: solid masonry, lime mortar, slate or terracotta, timber sash windows, ornamental render. Those trades and materials cost more than a modern rebuild, and a standard replacement-cost calculator doesn't know that.
Heritage Approvals and Professional Fees
Reinstating a listed building can need heritage approval as well as a building permit, with a heritage architect or conservation consultant in the loop. Those fees, and the time they add, belong in the sum insured alongside demolition and debris removal.
Purchase Price Is Not Rebuild Cost
Regional heritage homes can sell for less than they cost to rebuild. In one regional South Australian placement, the property was bought for a little over $200,000 and the rebuild estimate sat closer to $400,000. A sum insured set at the purchase price would have left the owner short by well over $150,000.
The Listed Element May Have to Come Back
If the facade or another element is listed, the heritage body may require that element to be reinstated to its former condition even where the rest of the building is a total loss and cash-settled. Ask the state or local heritage authority what would apply before setting the figure.
Documented Upgrades Change the Rating
Older buildings raise questions about wiring, plumbing and the switchboard. A full rewire, new switchboard, replumbing or a reroof, with dates, is usually what moves a listed building from a referral to an approval, and it changes the premium.
Loss of Rent Over a Longer Rebuild
Heritage approvals and specialist trades stretch the rebuild period. The loss of rent limit should cover the weekly rent for a realistic reinstatement period on a listed building, which is usually longer than for a standard house.
What it costs: Recent Tank placements for heritage-listed residential rentals have landed between around $3,000 and approximately $4,200 a year, and in one South Australian placement the spread between two insurers on the same listed building was more than double. Your property will be rated on its own details. See the landlord insurance cost guide for the wider picture.
03WHO WRITES IT
The Markets That Write Heritage, and What Happens After a Loss
Listed residential buildings are usually placed by referral. Instead of an online quote, the file goes to an underwriter who reads the listing, the construction, the upgrade history and the sum insured, and decides on the building in front of them. Some mainstream landlord insurers will approve a referral on a listed house; specialist markets assess the harder ones, such as former commercial buildings converted to residential or period homes with no documented upgrade history.
Each underwriter weighs those factors differently, so a listed building sits inside one market's appetite and outside the next. That is why a decline elsewhere is information about the insurer, not a verdict on the property, and why the submission matters more here than on a standard rental.
After a major loss, the heritage authority becomes part of the rebuild. On a state-listed or locally listed property, depending on the state and the register, the body that administers the listing can require the listed element to be reinstated to its former condition, and can require approval of the reinstatement design before work starts. The policy pays up to the sum insured, plus loss of rent within its limit; the obligations sit with you as owner. Knowing what they are before a loss is what keeps the sum insured honest.
WHAT TO PREPARE
Six things that make a listed rental quotable
-
The listing
Which register the property sits on (state heritage register, local heritage item, or a heritage overlay or conservation area) and which elements are listed, facade only or the whole building.
-
A rebuild estimate
A replacement-cost estimate or valuation that accounts for heritage materials, approvals and professional fees, not the purchase price.
-
Upgrade history
Dates for rewiring, switchboard replacement, replumbing, reroofing and any structural work, with invoices or certificates where you have them.
-
Occupancy and rent
Whether the property is tenanted, the weekly rent, the lease term and whether a property manager is involved.
-
Claims and condition
Any claims in the last five years, and the current condition of the roof, gutters, stumps or footings and drainage.
-
Your heritage obligations
What the heritage authority has told you would apply after a total loss. If you haven't asked yet, ask before the sum insured is set.
CLIENT SUCCESS
Listed Buildings, Rented Out: How These Risks Actually Get Placed
Recent Tank placements, anonymised. Premiums are approximate gross figures and reflect each risk at the time - not a guide to future pricing or turnaround.
Premiums and outcomes described are specific to each client and indicative only. Your own terms will depend on your circumstances and the insurer.
HERITAGE RENTAL FAQS
Common Questions About Insuring a Heritage-Listed Rental
RELATED COVER & GUIDES
More on Heritage and Landlord Cover
Got a listed rental, a decline, or a sum insured you're not sure about? Send us the details and we'll review it.
Talk to Our Team →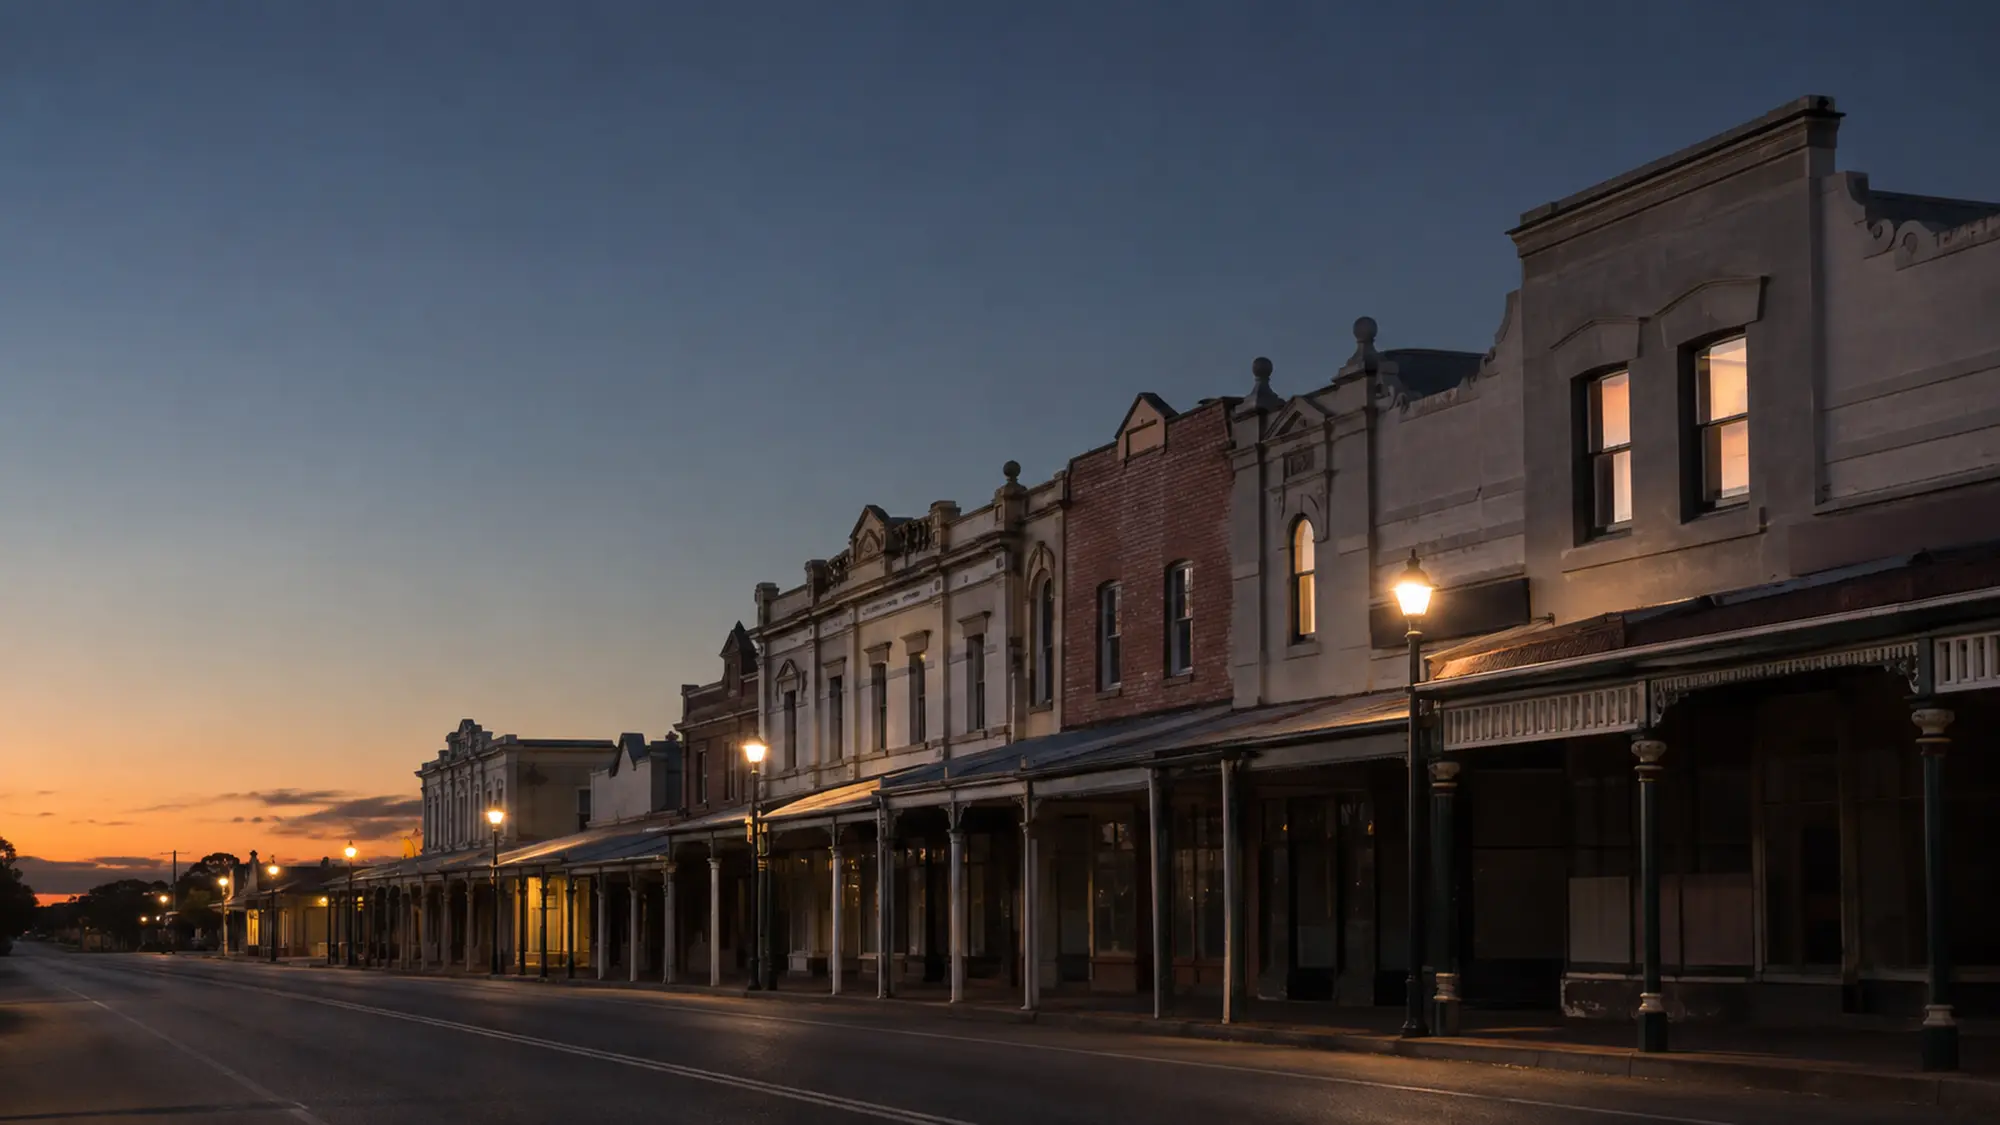
Get a Heritage Rental Property Insurance Quote
Tell us what's listed, what's been upgraded and what it would cost to rebuild. We'll come back with terms from the markets that write it.