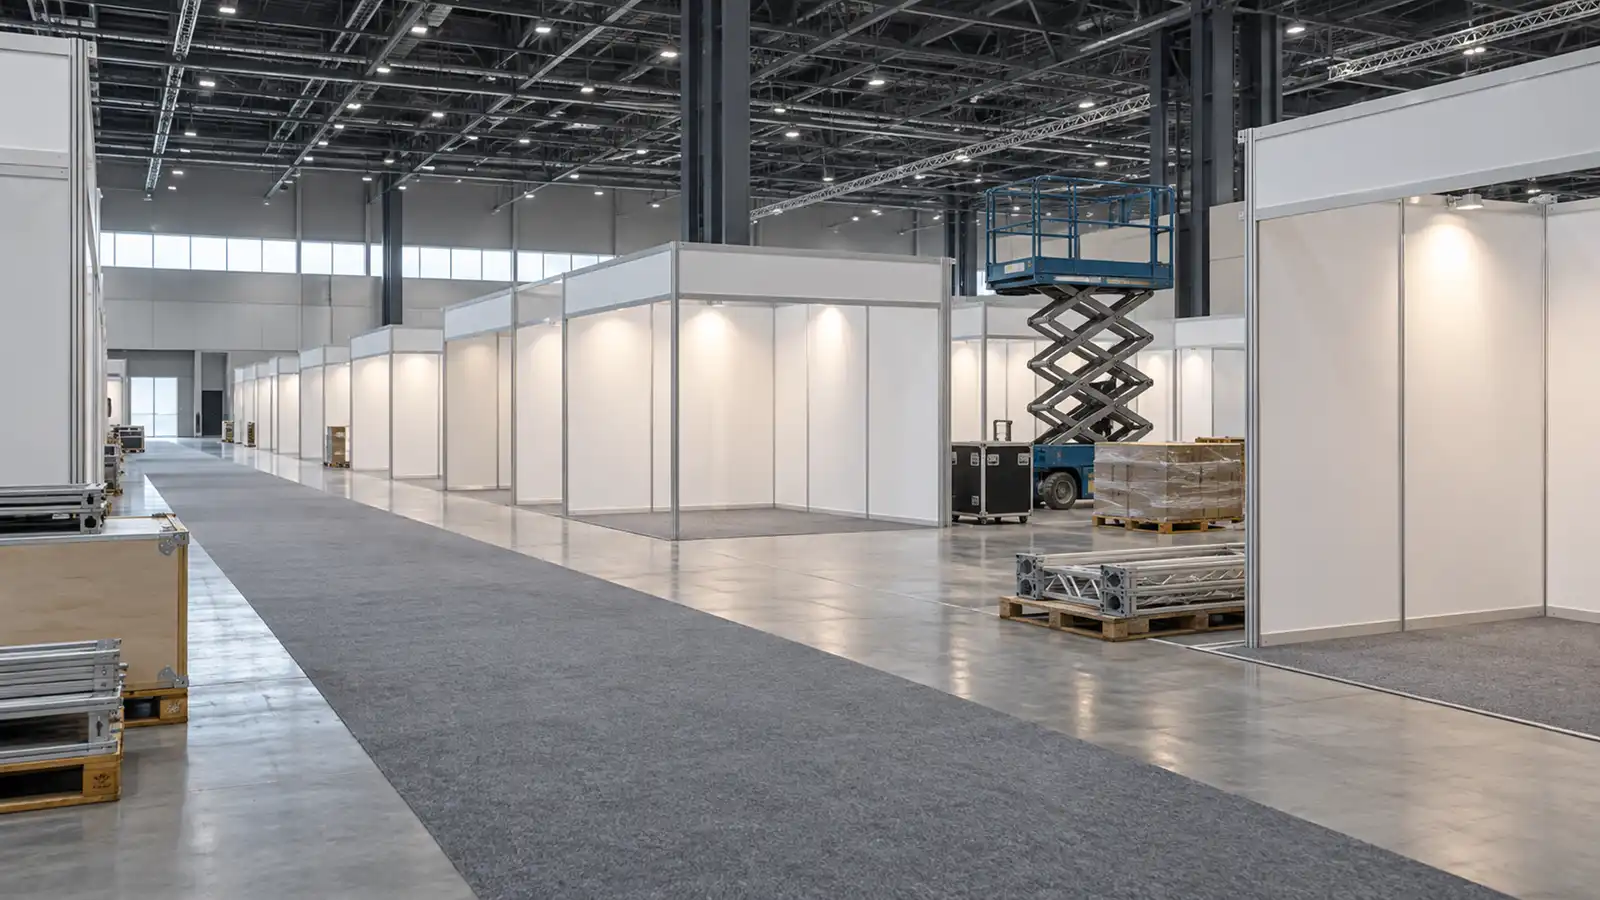
Exhibition hall during bump-in with blank booths, conference and exhibition insurance

EVENT INSURANCE

Conference and Exhibition Insurance

By the time a conference opens, the venue deposit, catering minimums, speaker fees and marketing are already spent. Cancellation cover can protect that money if the event cannot go ahead for an insured reason. Public liability keeps the venue happy. Here is how the two fit together, and where exhibitors and speakers come in.

Cancellation + PLThe usual conference package
SeparateHow speaker non-appearance is usually bought
$10M or $20MExhibitor public liability organisers ask for
Not coveredLow registrations or weak sponsorship

Premiums and outcomes described are specific to this client and indicative only. Your own terms will depend on your circumstances and the insurer.

THE SHORT ANSWER

What insurance does a conference, exhibition or trade show need?

Conference and exhibition insurance is usually event cancellation packaged with public liability, with speaker non-appearance added as a separate section. Cancellation pays the costs you cannot recover, or lost revenue if you insure on that basis, when the event is cancelled, postponed or relocated for reasons outside your control. It does not cover low registrations or weak sponsorship. Public liability, usually $20 million, covers injury to delegates and damage to the venue, and exhibitors are commonly required to hold their own $10 million or $20 million cover or be included in cover the organiser arranges.

Cancellation is priced against the sum insured, and rates vary between events, so we price each conference on its own budget and program. Minimum premiums apply.

Usual package
Cancellation plus public liability
Speaker non-appearance
Usually a separate section
Low attendance
Not covered
Communicable disease
Generally excluded
Shaneel Gounden

Our events specialist

Shaneel Gounden

Account Executive

Conference cover is commonly packaged as event cancellation with public liability included. Non-appearance of speakers is handled separately, as its own section.

Previously in the Entertainment and Sports team at Marsh, placing event liability, cancellation and prize cover, then in events at Aon.

General information only. It does not take into account your objectives, financial situation or needs. Consider the relevant PDS and TMD before deciding, and cover is subject to the policy terms.

SectionWhat it pays forWhat to know
Cancellation and abandonmentCosts you cannot recover (or lost revenue, if insured on that basis) when the event is cancelled, postponed, relocated or cut short for reasons outside your controlLow registrations and weak sponsorship are not covered
Speaker non-appearanceLosses when a named speaker cannot attend through illness, accident or travel disruptionUsually a separate section; some packages include a limited version
Public liabilityInjury to delegates and visitors, and damage to the venue caused by your negligence$20M is the usual venue requirement
Terrorism, civil commotion, national mourningCancellation caused by those eventsVaries by insurer: some include, some sell as extensions, some exclude
Communicable diseaseCancellation because of an outbreakGenerally excluded since COVID
Adverse weatherCancellation caused by severe weatherSome wordings limit it to open-air and marquee events
General information only. Cover depends on the policy wording, and wordings differ between insurers.

Published cancellation wordings generally exclude losses from the level of public interest, poor ticket or registration sales and lack of sponsor support. If delegates simply do not register, that is a financial risk the organiser carries. Cancellation cover is for events that cannot go ahead: the venue is damaged or unavailable, authorities close it, severe weather cuts access, or another insured cause stops the event.

Many wordings reduce a claim if the amount insured is below the full budget, so organisers generally insure the full amount they stand to lose. At least one published wording pays on a net loss basis and reduces the claim proportionately when the sum insured is less than the true budget. More detail is on the event cancellation insurance page.

Non-appearance cover names the people the event depends on, with their dates of birth and role. Insurers ask for health declarations from each person, their travel plans and arrival times, and whether a substitute could step in. For international keynotes, allow a buffer between arrival and the session; underwriters ask about it.

A loss adjuster usually investigates a claim, and the key question is whether the event can be rescheduled. If it can, cover typically pays the costs of moving it, subject to the wording. Some conference packages include a limited version of speaker cover; key-speaker cover for a named headliner is usually bought on top. See non-appearance insurance.

Exhibitors

Their own public liability

Organisers and venues commonly require every exhibitor to hold public liability of $10 million or $20 million for the exhibition, including move-in and move-out. Set the limit in your exhibitor manual to match what the venue requires of you.
Schemes

Organiser-arranged exhibitor cover

Some organisers arrange cover that automatically includes every exhibitor. Schemes differ: published examples run at $10 million or $20 million, and some exclude damage caused by the exhibitors' own products. Check the limit against the venue's requirement before relying on it.

Exhibitor side

Late or damaged exhibits

Some cancellation wordings include an inability-to-proceed trigger for when essential equipment, exhibits or stock arrive late or damaged. It is worth asking about if a stand is expensive to build and ship.

Venue

Damage to the venue

Public liability responds to damage you negligently cause to the venue, but property in your care, custody or control can be sub-limited. In our events specialist's experience, damage to hired halls and venues (floors and fittings) is among the most common event liability claims. Whether one is paid depends on the facts, the hire agreement and the wording.

Contract

Indemnities in the venue agreement

Venue contracts often ask the organiser to indemnify the venue. Some event liability wordings exclude hold harmless agreements unless the insurer has reviewed them. Send us the venue contract before you sign it.

Help

Where we fit

We can review the insurance clauses in your exhibitor manual, so the requirement you set is one exhibitors can actually meet.

Insurers usually require cancellation cover to be bound and paid well before the event, often weeks ahead, and anything already known when you buy it is excluded. In our events specialist's experience, many single-event quotes are not released more than about 90 days out. For an association that runs an annual conference, an annual policy is another way to secure cover early, it can price competitively against single-event cover depending on the calendar, and it can include the association's office risks for the rest of the year. Associations running regular events often also consider management liability for the committee.

Before joining Tank, Shaneel worked in the Entertainment and Sports team at Marsh, placing event liability and event cancellation for associations, event managers and promoters.

FREQUENTLY ASKED QUESTIONS

Conference and Exhibition Insurance FAQs

It depends on how much you would lose if it could not go ahead. Add up the venue deposit, catering minimums, AV, speaker fees and marketing that you could not get back. That total is what you would insure, and the premium is priced against it, so we can take it to market for terms once we have the budget and the event details.
No. A shortfall in attendance or sponsorship is treated as financial failure and is excluded from standard cancellation wordings. Where a package includes a reduced-attendance section, it generally responds only when delegates cannot attend because of an insured event, not because demand was soft.
Many standard cancellation wordings exclude non-appearance, so organisers typically add a speaker non-appearance section naming the people the event depends on. Insurers ask for dates of birth, health declarations and travel plans, and a loss adjuster usually investigates a claim. The key question is whether the session or event can be rescheduled.
Usually, yes. Many venues and organisers require each exhibitor to hold $10 million or $20 million public liability, unless the organiser arranges cover that includes them. Set the requirement in your exhibitor manual and collect certificates before move-in.
Standard cancellation wordings generally exclude war, and terrorism cover varies by insurer. Anything already known when you buy the policy is excluded too, so if international speakers or delegates may be affected by a conflict or travel advisory, raise it before binding, not after.
Damage you negligently cause to the venue is the kind of claim public liability is there for, but damage to property in your care can be sub-limited, and ordinary wear is not covered. Read the venue agreement's damage and indemnity clauses alongside your policy.

QUOTE REQUEST

Get a conference or exhibition insurance quote

Tell us the event dates and venue, expected delegates and exhibitors, the budget you want to protect, any speakers the program depends on, and the limit the venue requires.

Specialist broker review Australian business insurance
Empty event hall after pack-down with house lights low, event insurance arranged with Tank

Protect the Budget You Have Already Spent

Venue deposits and speaker fees go out months before the doors open. Send us the budget and venue contract and we will set out what cancellation, liability and speaker cover would look like.

Last updated: 01/10/2026

Call Us Now +61 2 9000 1155