Contents
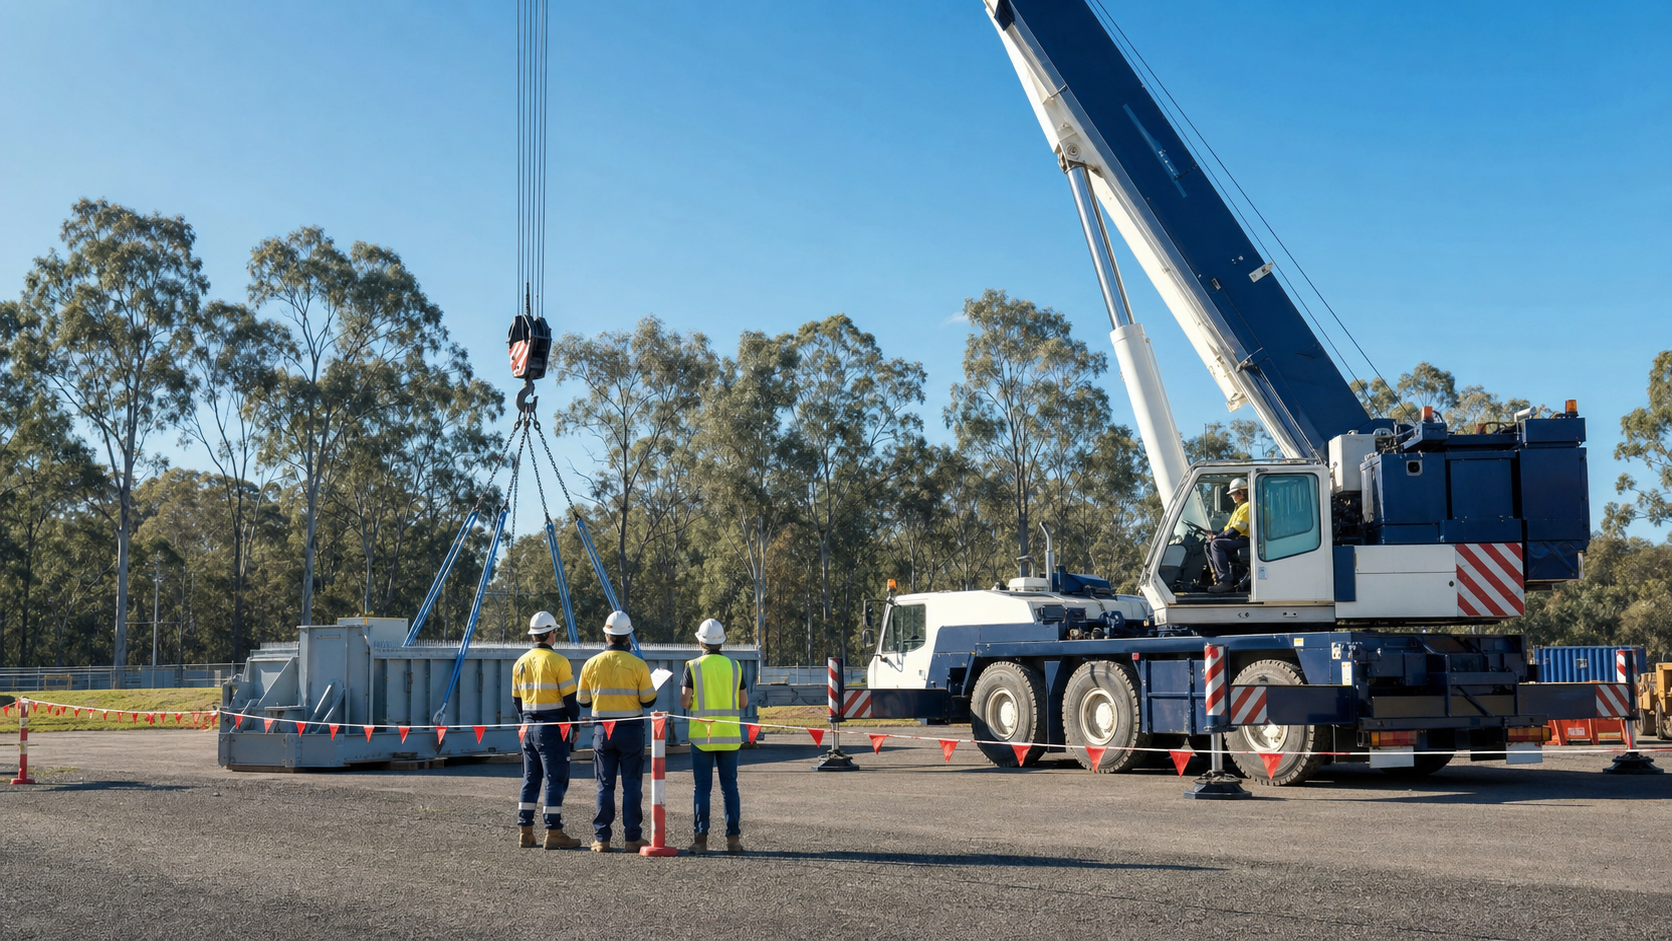
A crane operator and a crane owner can be different businesses. One controls the lift, another owns the plant, and a third party may hire the complete service. Insurance needs to follow those roles rather than assuming the crane’s policy covers everyone.
In 2026, a clear contract and responsibility map is the fastest way to separate plant damage from operating liability.
How does crane operator insurance differ from plant owner insurance?
Crane operator insurance focuses on the services and liability of the operating business. Plant owner insurance focuses on the physical asset and the owner’s contractual interests. A business performing both roles needs both sets of questions answered.
Tank’s crane insurance guide gives the industry overview. This role matrix makes the split visible.
| Role | Main responsibility question | Cover to discuss |
|---|---|---|
| Crane owner | Is the machine damaged, stolen or broken down? | Plant material damage or machinery breakdown |
| Crane operator | Is there an allegation about operating the lift? | Public liability, subject to wording |
| Wet-hire provider | Who supplies and directs the operator? | Plant plus service liability |
| Dry-hire provider | Who has possession and control? | Plant hire and contractual cover |
| Principal contractor | Who controls the site and lift plan? | Project and liability programme |
Wet hire supplies plant with an operator or service. Dry hire supplies the plant without the owner’s operator. Those definitions create different control and contract evidence.
Who insures damage to the crane?
The owner can arrange plant material-damage cover, but the hire contract may allocate responsibility to the hirer for some events. That doesn’t mean the hirer’s liability policy automatically pays for the crane.
Check the plant schedule, insured value, attachments, boom or jib, lifting accessories, road registration, transit and recovery costs. For mobile cranes, the commercial motor insurance guide helps separate road use from plant operation.
If the equipment is dry hired, Tank’s dry-hire insurance page explains the possession and contract questions.
Who insures the operating service?
The operating business can face allegations that its work caused injury or property damage. The public liability insurance guide explains that third-party layer, subject to declared activities, height, lifting and exclusion terms.
Safe Work Australia says certain plant operations require a high-risk work licence and directs people to their jurisdiction’s regulator through its high-risk work licensing guidance. Licensing doesn’t determine insurance cover, but it is important evidence about authorised operators and work classes.
The submission can also include lift planning, ground assessment, exclusion zones, maintenance and communication procedures. State the facts without claiming that a safety system guarantees an insurance outcome.
What should the contract allocation map record?
Before comparing policies, put the job into a one-page map:
- Registered owner and operator details, where applicable.
- Employer or engager of each operator and dogger.
- Wet-hire or dry-hire arrangement.
- Party directing the lift and approving the lift plan.
- Responsibility for maintenance, inspection and certification.
- Responsibility for ground conditions and site access.
- Contract terms for damage, indemnities and insurance.
- Plant value, attachments and maximum lifting activities.
- Required liability limits and claims history.
Then compare the map against the schedule, business description and endorsements. A certificate of currency alone may not reveal every restriction.
Frequently asked questions
Does a crane operator need to own the crane to have liability exposure?
No. Operating or controlling work can create liability questions even where another party owns the crane.
Does plant insurance cover operator negligence?
Not automatically. Physical damage to plant and allegations about operating work can fall under different policy sections.
What is the insurance difference between wet hire and dry hire?
Wet hire includes an operator or service, while dry hire supplies the plant without the owner’s operator. The contracts and policies need to reflect that difference.
To discuss a role and contract map, contact Tank Insurance on 02 9000 1155 or [email protected].